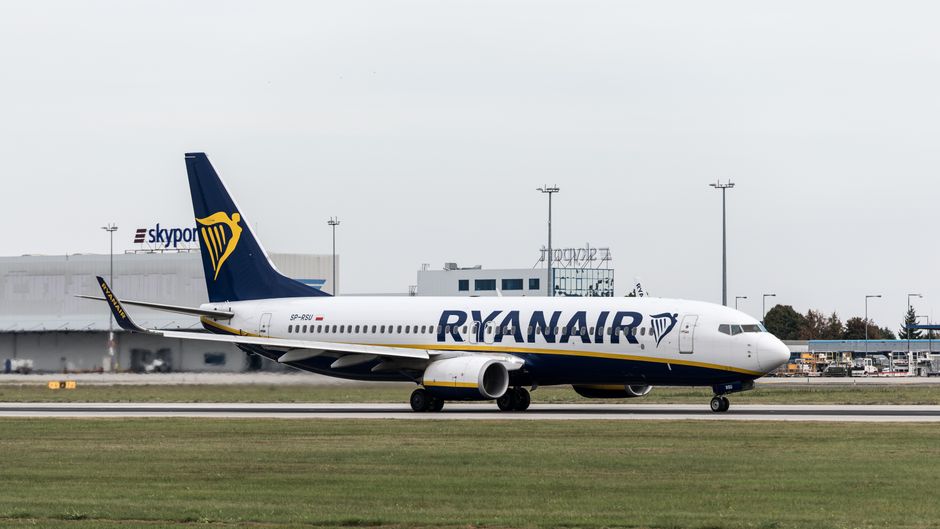
JPMorgan Chase & Co. has raised concerns about the implications of jet fuel supply shortages for European airlines, cautioning that the constraint poses a material risk to earnings guidance across the sector. In its assessment, the bank identified London-based International Airlines Group as the airline operator best positioned to navigate current pressures stemming from aircraft fuel availability challenges.
The warning reflects broader supply chain pressures affecting the aviation industry as carriers attempt to maintain flight schedules against a backdrop of constrained fuel availability. Jet fuel represents one of the largest operational cost components for airlines, with supply fluctuations directly impacting profitability and the sustainability of forward-looking financial guidance that management teams have provided to investors.
Sector-Wide Pressure
The jet fuel shortage presents a particularly acute challenge for European carriers that operate dense route networks requiring substantial fuel inventories. Airlines across the region have faced mounting pressure to secure adequate supplies while contending with volatile pricing dynamics. The situation has prompted financial institutions to reassess earnings forecasts and risk profiles across the aviation sector.
JPMorgan’s analysis suggests that not all carriers possess equal capacity to absorb or mitigate the impact of fuel supply constraints. The differentiation in resilience reflects variations in fleet composition, route economics, hedging strategies, and overall financial flexibility. Airlines with diversified revenue streams, efficient operations, and stronger balance sheets retain greater capacity to absorb shocks without compromising previously issued guidance.
IAG’s Competitive Advantage
International Airlines Group, which operates multiple major European carriers, emerged from JPMorgan’s assessment as the sector participant best equipped to withstand current pressures. The London-listed airline group’s positioning stems from factors including operational scale, cost management capabilities, and financial resources that provide cushion against near-term supply-side challenges.
The endorsement carries significance for investor perception of relative risk within the European airline sector. Airlines facing tighter margins or less diversified business models confront greater risk of guidance revisions should fuel supply constraints persist or intensify. The stark difference in positioning underscores how operational and financial structure determines resilience during periods of sector-wide stress.
Market Implications
The JPMorgan assessment highlights ongoing vulnerabilities within European aviation despite recovery from pandemic-related disruptions. Supply chain resilience remains fragile, with fuel availability emerging as a constraint distinct from demand-related pressures. The warning suggests that investors cannot assume smooth execution of airline earnings forecasts based solely on underlying demand metrics.
For European financial markets, the analysis reinforces the importance of differentiating between sector participants based on structural resilience. Capital allocation toward airlines requires careful consideration of individual companies’ capacity to navigate supply-side shocks. As the sector transitions toward sustainable growth trajectories, the ability to secure critical inputs and manage associated costs will increasingly differentiate winners from more vulnerable competitors within Europe’s aviation ecosystem.